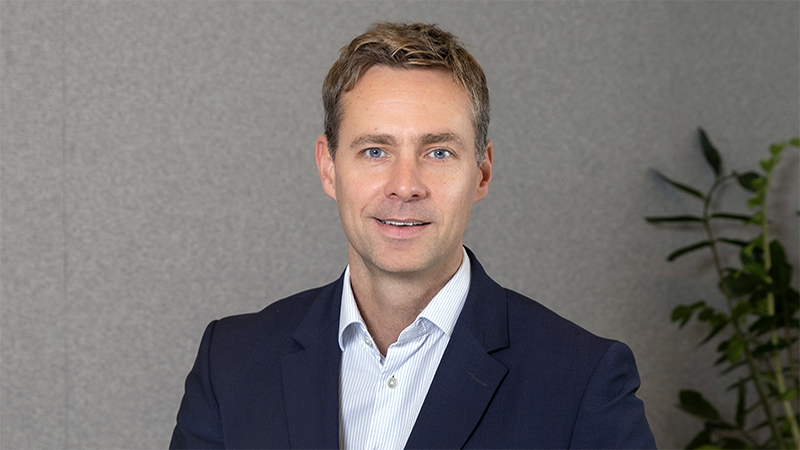
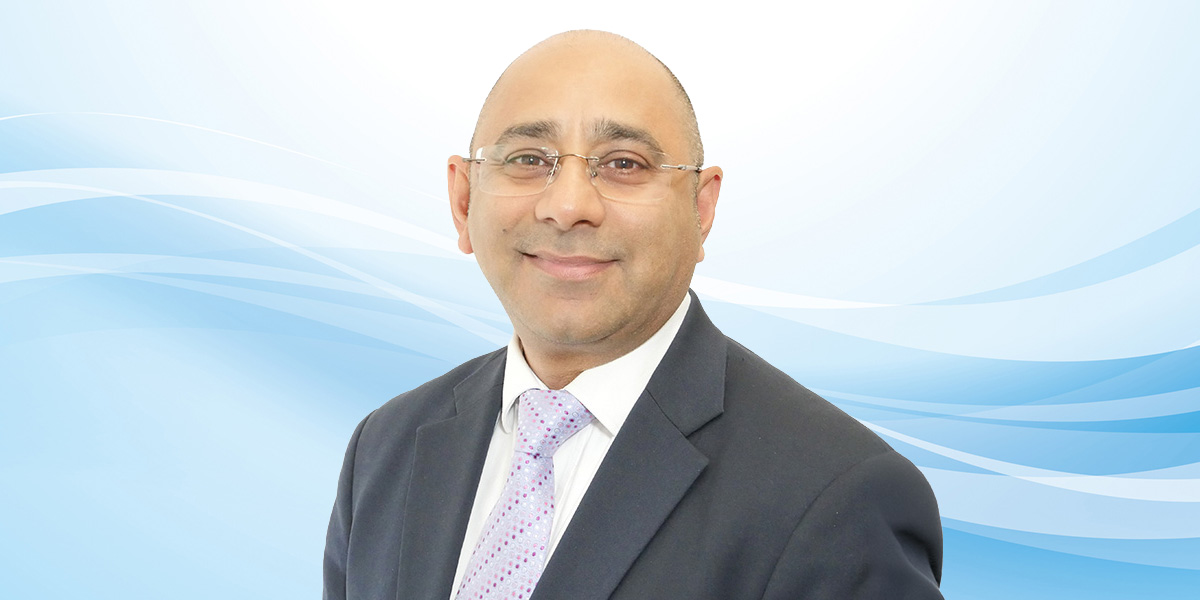


Despite 30 years investing in bond markets, Nedgroup Global Strategic Bond fund manager David Roberts (pictured) has never seen much value in Japan.
Things have changed in recent months, however. With yields spiking, the former Liontrust head of global bonds is buying long-dated Japanese government bonds for the first time in his career.
He says the recent movements in the JGB market are reminiscent of the 2022 gilts crisis that followed the UK’s mini-budget.
“Japan’s going through that moment it would appear, albeit in a more orderly fashion when it comes to long-dated bonds.”
Why are JGB yields rising?
Japan has previously maintained extremely low interest rates after pushing them into negative territory in 2016. JGBs have offered minimal real returns in recent years because of this, making them unattractive to global investors when compared with other government bonds.
That began to change when Japan ended the era of negative interest rates last year. In recent months, political and fiscal uncertainty has driven yields sharply higher, sending the 30-year JGB yield above 3% to its highest level in decades.
“There has never really been value in Japan, but things have changed,” Roberts says.
Roberts, who runs the Nedgroup Global Strategic Bond fund alongside Alex Ralph, was previously head of fixed income at Kames Capital (now Aegon AM).
He says part of the opportunity comes in the difference in yield between 10-year JGBs, which currently yield around 1.5%, and longer-date 30-year bonds.
“The difference between those two has widened significantly,” Roberts says. “The curve has steepened, which is something we’ve seen in lots of other countries.”
See also: AVI Japan and Fidelity Japan trusts agree heads of terms over merger
An unusual steepening
The Japanese yield curve has steepened at a time when the Bank of Japan (BoJ) is expected to raise interest rates. Normally, yield curves steepen when central banks are cutting rates, as seen in the US.
Roberts points to two main reasons for the unusual steepening. First of all, Japan has ended yield curve control after decades of manipulating bond prices. Until earlier this year, the BoJ set yield targets and bought unlimited amounts of bonds if yields exceeded those target levels.
Another factor is the relative strength of the Japanese economy, which has been performing well.
“Inflation has been above the BoJ’s target for the last three years,” Roberts says. “They should have raised rates aggressively, but they have failed to do so. The market now fears inflation is becoming embedded. If consumers start demanding a better standard of living, that could drive governments to introduce welfare packages and increase borrowing, much like in the UK, which is stimulatory from an economic perspective and potentially inflationary.”
This, he explains, has hit 30-year bond prices harder than shorter-dated bonds, which remain attractive to domestic investors for their income profile.
Since the snap election in October 2024, Shigeru Ishiba’s Liberal Democratic Party (LDP) has led a minority government, relying on opposition support to pass legislation. In July’s elections to the House of Representatives, the LDP lost 18 seats and saw its vote share fall further, though it remains the largest party. The necessity to rely on smaller parties to pass through its agenda has led to concerns over concessions leading to greater government spending.
“It’s unusual for the Liberal Party not to be solely in power,” Roberts says. “The fear in the market is that shifting politics could mean greater fiscal spending. It’s already priced in to some extent which creates the potential for yields, especially long-dated ones, to fall.”
PA event: Autumn Congress 2025
Roberts also notes his team always hedges currency risk, which adds to the relative attraction of JGBs.
“If we buy Japanese bonds, we hedge the yen. At this moment in time, the yield differential between UK base rates and the Japanese equivalent is 3.5%, so I’m paid that extra to hedge. Our 30-year JGBs yield 3.1%; add the 3.5% from hedging and you get about 6.6%, compared with just over 5% for UK gilts. So we’re being paid almost 2% more to own Japanese assets.
“There are huge value opportunities. We know why they exist, and they compare very favourably with Germany, the UK, or the US — especially when we remove currency risk.”
Iain Stealey, International CIO of fixed income at JP Morgan Asset Management, also sees value in the Japanese bond market.
“Long-maturity Japanese bonds offer an attractive yield pickup,” he says. “The Japanese government bond yield curve is very steep compared to other major developed bond markets. The recent spike in yield reflects a lack of structural demand from domestic buyers, and investors worry about the fiscal outlook in Japan.
“However, the Japanese Ministry of Finance is taking steps to correct the demand/supply imbalances, and the fiscal position in Japan is actually at its best level in decades. The BoJ is expected to resume hiking rates, which could increase the relative attractiveness of long-maturity bonds.”