Building a solid position in the UK concrete sector
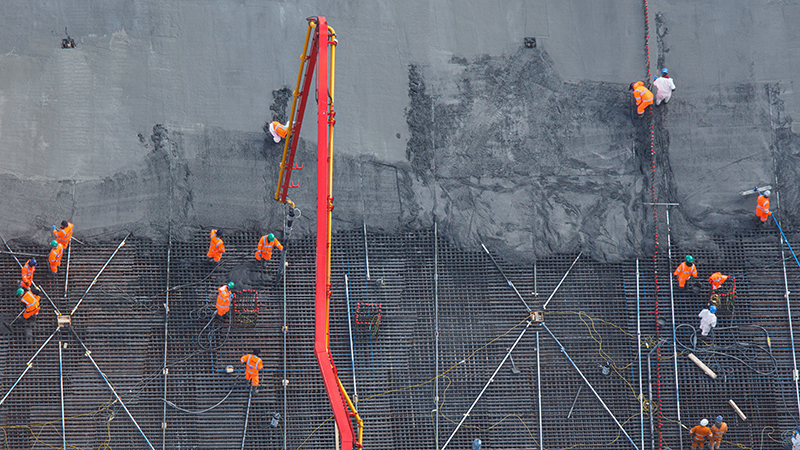
Housebuilding has been a struggling area of the UK market for a while now, as construction slides and volumes remain low, but for some portfolio managers this has made construction businesses an interesting area to seek opportunities in.
This is the case for Simon Gergel, manager of the Merchants Trust.
“All of our holdings start with the bottom-up investment case, but sometimes several companies with similar characteristics are compelling, and we can recognise a connected theme in the portfolio.
“The UK housing, infrastructure and RMI (repair, maintenance and improvement) markets are generating a lot of very compelling ideas at the moment, as the market seems to have given up on a cyclical recovery,” he explains.
Gergel owns Breedon Group, a leader in cement, aggregate and concrete in the UK and increasingly in the US midwest. Since initially purchasing the stock in March, it has grown to around 2% of the total portfolio, a relatively average position size, he says.
Part of the thesis for buying the stock was the disconnect between the “excellent market position backed by real assets”, alongside a low valuation and activity suppressed by a cyclical downturn, according to the Allianz manager.
“The valuation, as can often be the case with cyclical companies, forgets the cycle, and assumes poor conditions forever.”
On top of this, the company has an excellent runway for further growth. It essentially operates as an interesting “hybrid” business, he explains, with around 60% of the profits generated in the UK, with the rest split between Ireland and growing US midwest business.
“In Breedon’s case the mix is actually part of the appeal, since the US and Irish operations can offset a currently weaker UK market,” he says.
In the US, the company can grow “organically and inorganically” by consolidating smaller assets, while in the UK it can grow earnings significantly if the construction cycle turns, he says.
With UK cement volumes sliding to the lowest level since 1950, despite the UK population having surged 40%, Gergel sees huge pent-up demand for housing and infrastructure from which Breedon could benefit.
While he says European competition for cement could be a headwind, given the “mismatch in carbon regulation” between the EU and UK, “this should be resolved within a year or two”.
“Breedon is a business that has proven resilient in a poor environment for construction and infrastructure investment but can grow earnings very substantially in a better environment.
“As with any cyclical business, the cycle can always take longer or get worse, but we observe that Breedon has defended its profit margins very well through the downturn in mitigation.
“We believe the market undervalues both the current strength of the US business within the group and the recovery potential of the UK,” he concludes.
Finding beauty in K- cosmetics
Emerging markets have had a truly fantastic year, with the MSCI Emerging Market index up 22.9% at the time of writing (18 September). At its peak, the index had rallied by more than 31% this year, according to data from FE fundinfo.
Most of this rally has been due to a handful of strongly-performing tech stocks, primarily in Korea and Taiwan, such as Taiwan Semiconductor Manufacturing Company, Samsung Electronics and SK Hynix. However, for Chris Tennant, portfolio manager of the Fidelity Emerging Markets Limited trust, there are still plenty of interesting opportunities in this market beyond tech.
For an example of a stock going under the radar, the Fidelity manager points to Cosmecca Korea, a beauty and skincare product manufacturer.
The team currently holds the stock at around a 0.9% allocation, having initially purchased it in June 2025 at a 0.4% weighting. Year to date, the stock is up 87%, according to data from Google Finance (as of 18 September).
While the holding in Cosmecca is primarily a company-specific opportunity, rather than a dedicated attempt to allocate to Korean beauty, there have been some wider tailwinds, according to Tennant.
“The rise in popularity of Korean beauty products, or ‘K-beauty’, has taken the global cosmetics world by storm, propelled by innovative products and fast-growing beauty trends,” Tennant explains.
“Behind many of the best-known brands sit more under-the-radar specialist manufacturers, such as Cosmecca Korea, which develops and produces skincare products on these brands’ behalf.”
Cosmecca is one of the largest manufacturers in the Korean market, he continues, so it is well-positioned to “ride the wave of strong demand” for Korean cosmetics. Scale is also a big boon, according to the Fidelity manager, helping it keep costs down and invest more in research and product development.
The Fidelity manager also highlights a handful of Cosmecca’s products, most notably its suncare range. Cosmecca’s suncare manufacturing in the US and its home market are both FDA-approved for over-the-counter products. This is a tailwind for its growth in the US market, where suncare is “over-regulated” as an over-the-counter product, he says.
“This gives the company an important advantage, helping it attract not only fast-growing Korean indie beauty brands, but also US customers,” Tennant adds.
That said, he acknowledges potential headwinds, such as “overly aggressive expansion” into other Asian markets. Significantly increasing the capex could weigh on profitability and even potentially dilute the margins, according to the manager.
“However, we would view this as a long-term positive, broadening the company’s geographic footprint and supporting future growth,” he says.
The Finnish retailer getting the job done
Small and mid-cap retailers may not be the most immediately popular part of European markets, but it’s an area with underappreciated potential, according to Jack Featherby, fund manager at the JPMorgan European Discovery Trust.
Within this sector, he owns a handful of names, including online fashion retailer Boozt and optical retailer Synsam, but one of the team’s largest positions is Finnish retailer Puuilo.
The firm operates in a “relatively niche” market, selling a range of affordable products for everyday life, such as DIY or maintenance, the JPM manager says. The Finnish market also tends to attract much less attention from international investors than larger European markets.
“Puuilo can easily fly under an investor’s radar,” Featherby concedes. “At first glance, it can look like a fairly simple retailer.” However, underneath the surface it has many attractive qualities, including strong-performing stores and a history of healthy cash generation and consistent market share gains, he explains.
“Opening a new store roughly every two months would be an ambitious target for most retailers,” Featherby says. “But for Puuilo, it forms part of a plan to roughly double its store network from around 40 to 80 over five years.”
The firm has a track record of efficiency, opening new stores with very little capital, but still achieving profitability and returning a substantial proportion of shareholders. Because it’s a relatively small business, each successful new store makes a meaningful contribution to growth, Featherby explains.
“To put this into perspective, Puuilo needs to open roughly one store every two months to achieve its growth target; a retailer like Walmart would need to open around eight stores a day to grow at the same rate.”
This growth is reflected in the share price, which is up more than 100% over the past five years, according to Google Finance data (statistics accurate as of 5 October).
Featherby and his team have owned the stock since March 2024, as it executed its growth strategy, but pulled profits in early 2025. That said, it is still one of their top 10 positions at the time of writing.
Looking ahead, Featherby is excited about the firm’s growth potential, particularly as it plans to expand into Swedish markets by early 2027 at the latest. “A successful expansion could also put this relatively under-the-radar Finnish company on the radar of a wider group of investors,” the JP Morgan manager says.
However, this expansion is not without risks, he concedes. On the one hand, it requires Puuilo to continue to maintain its high efficiency and successful stores against stiff competition from discount retailers and hardware stores.
“Growth could moderate if the domestic store rollout opportunity is more limited than management expects,” he notes. “Swedish expansion also adds another layer of execution risk. However, Puuilo intends to grow gradually and organically rather than relying on a large acquisition, limiting the amount of capital at risk as it tests the new market.”
Narrowing the Korean discount
Korea has surged this year, due to the strong performance of big tech stocks such as Samsung Electronics and SK Hynix, with the Korean Kospi up 55% (as of 14 October) in sterling terms.
However, before 2025, this market had struggled under persistent discounts, with the Kospi sliding double digits in both 2024 and 2023, according to FE fundinfo data. In 2022, it delivered an annual return of just 5.5% in sterling terms.
Ross McGarry, senior investment analyst at AVI Global Trust, notes: “Complex ownership structures, succession considerations and historically poor capital allocation have contributed to depressed valuations among many family-controlled Korean companies (the ‘Korea discount’).
“Entrenched chaebol structures, cross-shareholdings and poor capital allocation have left many high-quality Korean companies trading materially below the value of their underlying assets.”
One example of a discounted high-quality Korean name is Amorepacific Holdings, the South Korean family office holding company, which is responsible for some leading cosmetic brands in Asia, according to the AVI Global analyst.
The team first took a position in Amorepacific in June 2025 and has held it for roughly 15 months. During this period, it has mostly performed well, with operational earnings up 46% on a 12-month trailing basis.
Additionally, the valuation has arguably become more attractive, sliding from 20x to 15x forward Ebit, while the operational thesis has mostly strengthened, McGarry says.
But it could have much more room to grow, as it benefits from both a narrowing of the Korean discount and the spread of Korean beauty products in western markets, he adds.
“We believe the market continues to overlook both Amorepacific Corporation’s earnings growth and the inordinately wide 53% discount to net asset value at which Amorepacific Holdings trades.
“We believe government reform and growing shareholder pressure will encourage these companies to improve governance, capital allocation and shareholder returns.
“If the current reform momentum is sustained, stronger governance and rising shareholder activism could unlock this value and support a broader re-rating of the Korean market,” the analyst concludes.
The trust maintains an allocation in Korean stocks more generally beyond just Amorepacific. According to the firm’s August factsheet, it has a 20% allocation towards Korean companies on a look-through basis; it is its third-largest geographical allocation.
On top of this, McGarry argues the stock is well supported due to its position in the Korean beauty sector and strong brands.
“CosRX is a key example of what we call a ‘K-beauty disruptor’,” the AVI analyst adds. “The brand has built a large gen-Z and millennial customer base, with its snail-mucin skincare going viral on social media and becoming one of Amazon’s best-selling facial serums.”
He also points to Sulwhasoo, one of the firm’s longest-standing luxury brands.
“It exemplifies the group’s heritage of combining traditional Korean herbal ingredients with modern skincare research, having launched the world’s first ginseng-based cosmetic product in 1966.”
Bridging the gap in agriculture
Finding companies that span multiple assets and areas can be challenging, much less when investors have a global universe of stocks to choose from. But for Richard Clode, co-manager of the Bankers Investment Trust, one standout is Vylor, a seed and genetic company that spun off from American business Corteva.
The Janus Henderson team has held Vylor since the spinoff on 1 October 2026, continuing to add to its position as they built conviction in the thesis.
Part of the initial thesis, Clode says, was the company’s combination of market leadership, attractive intellectual property and long-term growth opportunities.
“It is one of the few companies in the world that sits at the intersection of agricultural productivity, biotechnology and food security, and is one of only a handful of global companies with the scale, intellectual property, distribution network and scientific capability to develop advanced seed genetics for farmers worldwide.
“What makes Vylor particularly interesting is that it combines three valuable assets: world-class germplasm and seed genetics; proprietary biotechnology traits; and a growing licensing business,” he adds.
Seed genetics is highly attractive in agriculture because farmers tend to seek the highest-yielding seeds, granting the best companies high pricing power, according to Clode.
“A telling statistic is that Vylor has never experienced a year of negative pricing, reflecting the value it delivers to customers.”
On top of this, developing new seeds requires years of testing, investment and innovation, giving established companies a compelling moat around the business, he adds.
Even the separation from the larger Corteva business was arguably a catalyst, he says. “We believe the seed business deserves a higher valuation multiple than the slower-growing crop protection business and that the spin-off will help unlock value by facilitating a higher multiple for a high-quality standalone company.”
Since the spin-off, the company has added around 11% from the initial price, and Janus Henderson’s team remains positive about the firm’s long-term potential.
“Vylor fits within the broad theme we describe as net zero 2.0, which, among other things, seeks companies that enable sustainable productivity growth, or growth with less environmental impact.
“We believe companies that help farmers produce higher yields more sustainably are likely to become increasingly valuable,” Clode explains. This will become even more apparent as global agriculture is forced to feed a growing population using fewer resources.
“We view agricultural innovation as a powerful long-term structural growth opportunity that remains underappreciated by many investors, especially as we witness increased climate volatility, including a more powerful El Niño this year,” the Janus Henderson manager adds.
That said, while Vylor is a strong example of this trend, Clode notes it is not the only expression of it within the portfolio, with the team also maintaining a holding in companies such as Novonesis, a BioSolutions business responsible for industrial enzymes for agriculture, industries, food and drinks.