
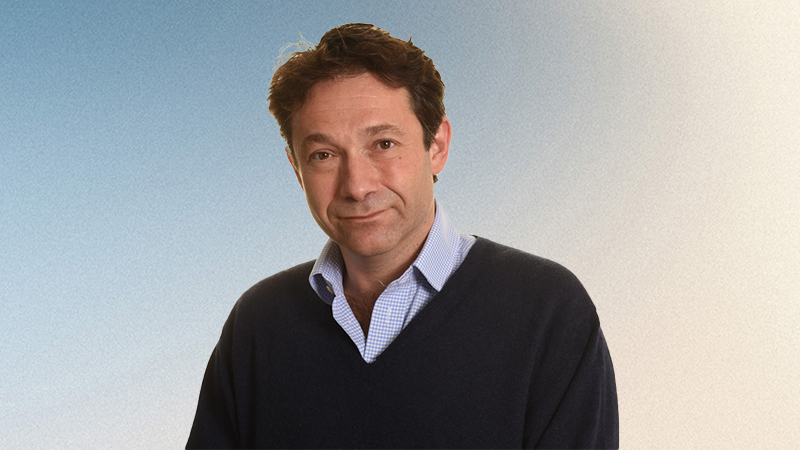

UK banks have struggled in the years following the global financial crisis, with their shares left languishing at discounts compared to global peers. However, Lansdowne Partners fund manager Peter Davies (pictured) argues the tide has turned.
Davies, who runs Lansdowne’s £430m daily dealing Developed Markets fund alongside Jonathon Regis and Nigel Hikmet, is a longstanding bull on UK banks. The fund is part of the £4.8bn Developed Markets strategy.He tells Portfolio Adviser a rare recovery play is unfolding in the sector, pointing to valuations that lag peers such as Australia and Canada by two to three times.
The team employs a research-driven process aimed at unearthing inconsistencies in the market, which often results in contrarian positioning.
See also: French 10-year yields overtake Italy as government falls
For instance, financials currently make up almost a third of the 37-stock portfolio, unusually for an IA Global sector fund. NatWest is the top holding at 8%, while Lloyds, Aviva and Bank of Ireland are also among the larger positions, reflecting the managers’ conviction that the market is mispricing risk in the sector.
NatWest’s share price is up over 50% over the last year, while Lloyds has risen over 35%. This has helped the fund to outpace its MSCI World benchmark since launch in December 2023, with the strategy up 44.2% compared to 28.9% for the market at the end of July.
Banks enjoy a unique advantage, Davies says. Banks can fund themselves through low-cost deposits, unlike other industries that must pay market rates for capital. These deposits also tend to be ‘sticky’, due to the hassle involved for customers in switching banks.
The industry also tends to expand faster than GDP, since money supply grows more rapidly than the broader economy, while high fixed costs drive consolidation in the sector.
“That combination, I would say, for 90 years out of 100 makes for a very good industry,” Davies says. “The problem is the other 10 years are the ones that people often remember for a period of time.”
“Certainly, in the UK and Ireland, it’s easy to understand why people over-remember the bad bits at the moment, given how deep the global financial crisis actually was.”
PA event: Autumn Congress
Part of the managers’ enthusiasm for banks comes due to the valuations in the sector in the UK and Ireland.
“Our basic thesis is actually a fairly straightforward one of normalisation. Banking is normally a pretty good business,” says Davies. “Even today, if you compare the value of banks in Australia, Canada and large parts of Asia to UK and Irish banks, it’s probably two or three times the market cap for industries which haven’t got as recent memory of a big crisis.”
He adds that following a crisis, risk premia are very high while risk appetite within banks is very low, meaning banks are often least risky just when markets assume the opposite.
Recent years support this point. Despite a cost-of-living crisis and record interest rate rises, provisions in the UK banking system have been about a third of pre-Covid levels.
“The very high risk premia are exactly when you have the most evidence that the core banking business is less risky than it normally is, which is what you’d expect,” Davies says.
Interest rates and earnings power
Headline returns can also look weaker than reality, Davies argued, because of the way UK banks hedge interest rates. “The hedge is depressing earnings materially for UK banks,” he says. “Ironically, headline earnings will rise very rapidly just because the hedge unwinds — and that’s been proven over the past 18 months.”
Future interest rate moves could also play to the sector’s advantage. Rather than rates falling across the curve, Davies expects the yield curve to steepen.
“If you end up with a steeper yield curve, then the negative effect from short-term interest rates coming down will be lower than either we’re forecasting or the markets are forecasting.
“That gives banks a fairly traditional maturity transformation opportunity we haven’t seen for a long time, and it will add to earnings.”
Combining these factors explains the fund’s conviction.
“The basic point is, it’s normally a good business. At the moment, if anything, it’s probably a better business than average, given the history. We can see very clearly why the rest of the market hasn’t spotted that.
“We’ve now got 18 months to two years of track record, so we’re very optimistic in the outlook for banks. The multiples are still very low. We think Lloyds and NatWest are on less than five times earnings at the end of the decade. For an industry that’s traditionally traded on 12–13 times and is very cash generative, we think that’s a pretty massive opportunity.”
The fund is part of the firm’s c.£4.8bn Developed Markets Strategy.