
Schroder Income Growth has released its full-year results for the 31 August 2026 year, with a share price total return of 23% and an NAV total return of 19%, compared with a FTSE All-Share Total return of roughly 21.3%
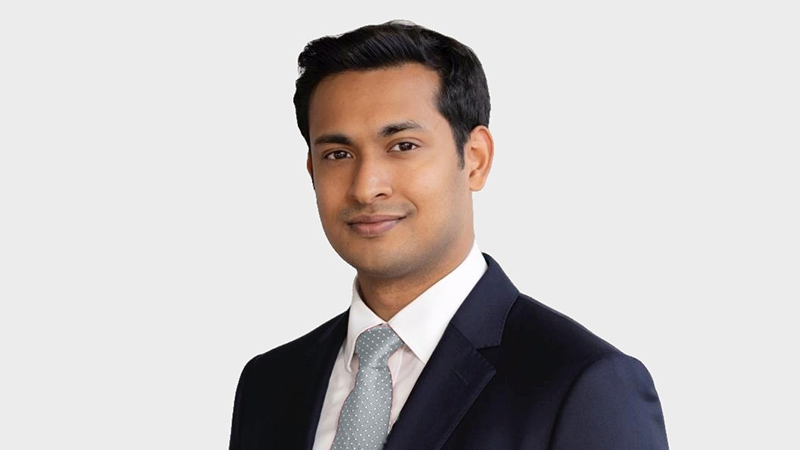
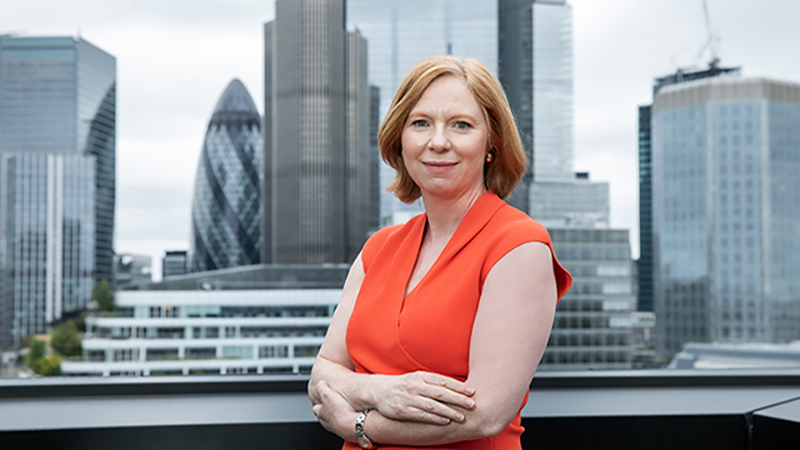
This marks a short-term underperformance from the trust compared with the wider UK market, which portfolio manager Sue Noffke (pictured) said was on a strong run.
“Despite the uncertain backdrop, resilient corporate earnings and economic activity proved supportive to markets, while the UK benefitted from its sector mix and elevated M&A activity, as overseas companies and private equity continued to take advantage of relatively low valuations,” she noted.
While the strategy mostly kept up, “it nevertheless trailed the index, with consumer discretionary, healthcare and financials the main sector detractors”.
Consumer discretionary, where the firm has an 8.5% allocation, was the largest headwind according to Noffke, as stocks like Burberry were hit by weaker demand for luxury goods. Meanwhile, others such as Whitbread faced volatility around the budget.
Ewen Cameron Watt, chair of the trust, added: “Whilst it is disappointing to lag Index returns at NAV level, the strong share price performance aided by share repurchases gave shareholders a competitive return in excess of the index.”
Indeed, the trust repurchased 4.4% of the trust’s currently issued share capital in share buybacks, narrowing the discount from 6.8% over the year to 5.3%.
Meanwhile, the trust grew its dividend for the 31st consecutive year, with dividends per share rising by about 4.1%, marking it as one of the AIC’s Dividend Heroes.
See also: Trusts versus funds: How do sibling investment vehicles stack up?
Noffke noted that while dividend income remained broadly unchanged between years, dividend growth was more varied across the market. For example, banks benefitted from higher-for-longer interest rates, while mining companies benefitted from higher commodity prices.
She said: “The way UK companies return capital to shareholders has changed materially in recent years. The pandemic prompted a significant reset in dividends, while attractive equity valuations have encouraged companies increasingly to combine ordinary dividends with share buybacks.
“As a result, ordinary dividends are generally better covered, while buybacks have become a more significant component of overall shareholder returns.”
This is demonstrated by the fact that by 31 August 2026, roughly 66% of the portfolio had announced share buybacks this year.
Richard Williams, senior analyst at QuotedData, added: “Solid absolute returns for SCF fell short of its benchmark gain, with weakness in consumer discretionary holdings proving a particular drag.
“More encouragingly, however, the trust delivered its 31st consecutive year of dividend growth and maintained its record of growing income ahead of inflation over the longer term.”
The combination of an active approach to discount management and a strong long-term dividend record remains attractive, although restoring full dividend cover would provide additional reassurance.”
While the short-term underperformance was “disappointing” for the Schroders team, over the longer term, the trust has generally outperformed the FTSE All Share since the manager’s appointment in July 2011.
According to FE fundinfo data over the past 10 years, the trust has delivered a 142.3% total return, compared with the FTSE All Share’s return of 122% over the same period.
See also: Tatton AM’s pre-tax profit soars 37% in half-year results