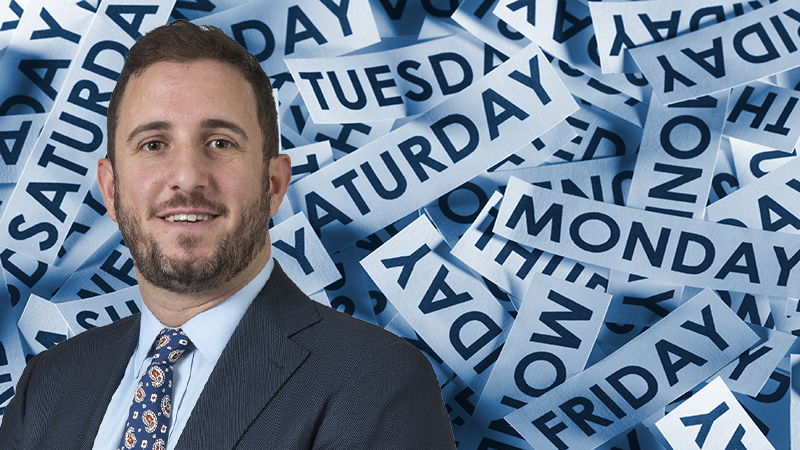
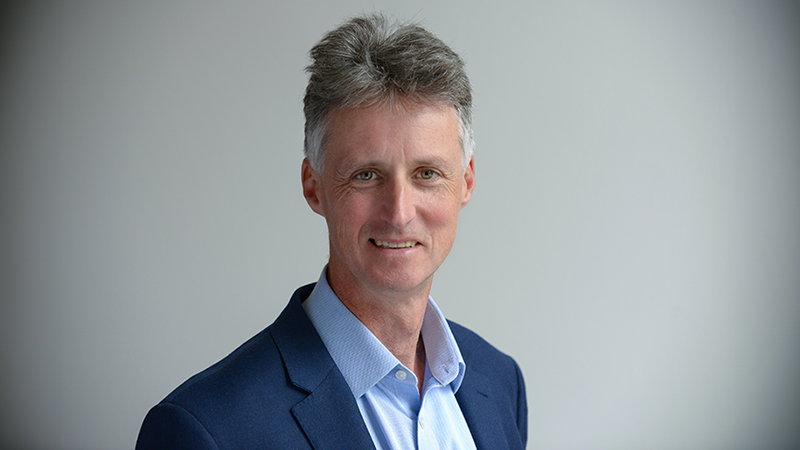

The Maven Renovar VCT board has defended its decision to change investment manager without a shareholder vote, in response to the requisition notice served by a group of investors led by former investment manager Amati Global Investors’ Dr Paul Jourdan (pictured).
The proposals include removing current board members Fiona Wollocombe, Brian Scouler, Neeta Patel and Robert Legget, and replacing them with Jourdan, Charles McMicking, Hector Kilpatrick and Kathleen McLeay as directors of the company.
The board said the requisition is “not in the best interest of shareholders”. However, the requisition notice filed on 30 June has been deemed valid, with the board convening the meeting “in due course”.
At a previous general meeting last month, shareholders rejected the re-election of the current directors and voted down a proposal to change the VCT’s investment strategy. The Maven Renovar board had claimed the proposals were rejected due to shareholders closely linked with Amati.
See also: What’s going on at Maven Renovar VCT?
Poor performance claims and Amati response
Amati was replaced by Maven as the investment manager in May following a strategic review.
Shareholders did not have a chance to vote on the decision to switch manager prior to being implemented. However, the board has today claimed the cost of Amati’s fees relative to the company’s losses was “wholly unsustainable” and the board had “no choice” but to change manager.
Meanwhile, the board has doubled down on its claim that the rejected votes at last month’s general meeting were influenced by shareholders ‘closely associated’ with Amati.
According to current board member Robert Legget, in the period between 1 February 2021 to the end of Amati’s tenure as investment manager, the VCT’s net asset value fell by £134.5m (after taking account of dividends, share buybacks and share issuances) while paying AGI fees of £14.5m, including a £1.1m termination fee.
“To see a former investment manager with such a dismal recent track record now seek to appoint himself and two of his fellow requisitioners to the board is quite extraordinary,” Leggett said. “Taken together, the proposed resolutions themselves are designed to be board-controlling and represent a nil premium takeover by a very small minority of Shareholders and are not in the interests of shareholders as a whole.”
See also: Why SJP is ‘significantly’ underweight in the US
In response, Amati contested the poor performance claims. According to the AIC, the average VCT AIM Quoted strategy is down 22.5% over the past three years to 30 June. Maven Renovar’s share price total return is down 24.8% over the same period.
“This is really a complaint about the whole of the AIM market, particularly the way early stage companies of the type in which the VCT has to invest have fared poorly,” said Amati’s Jourdan.
“The difference here is the change of manager was made in order to make a change to the investment policy. The signatories to the S303 [requisition notice] believe that the board should have given shareholders a vote on the change of investment policy before they made the change of manager, rather than presenting a fait accompli.
“The reason why the board were voted out at the AGM was because shareholders would rather make their own decision about buying a VCT with a different strategy. They wish this VCT to remain focused on AIM.”
Proposed director Hector Kilpatrick added he was “disappointed, but perhaps not surprised,” to note the board’s “decision to cherry pick a start date” for their performance analysis, which he claimed was an attempt to paint Amati’s management of the VCT in “a bad light”.
Amati’s Jourdan also called into question the board’s claims that the AGM votes were swayed by shareholders associated with the former investment manager.
“The board needs to demonstrate why they believe the AGM votes should not be regarded as representative of the wider shareholder base,” said Jourdan.
“The votes were carried by the shareholders who had the most at stake in the VCT and who have in many cases been investors for 10-20 years. They understand the VCT in great detail. Why would the interests of these shareholders be different from those of the wider base?”